Saturday, October 17

V11 Norton MP Temba Mliswa & Sister’s Vachifara In Mnangagwa’s House

V11 Norton MP Temba Mliswa & Sister’s  Vachifara In Mnangagwa’s House 

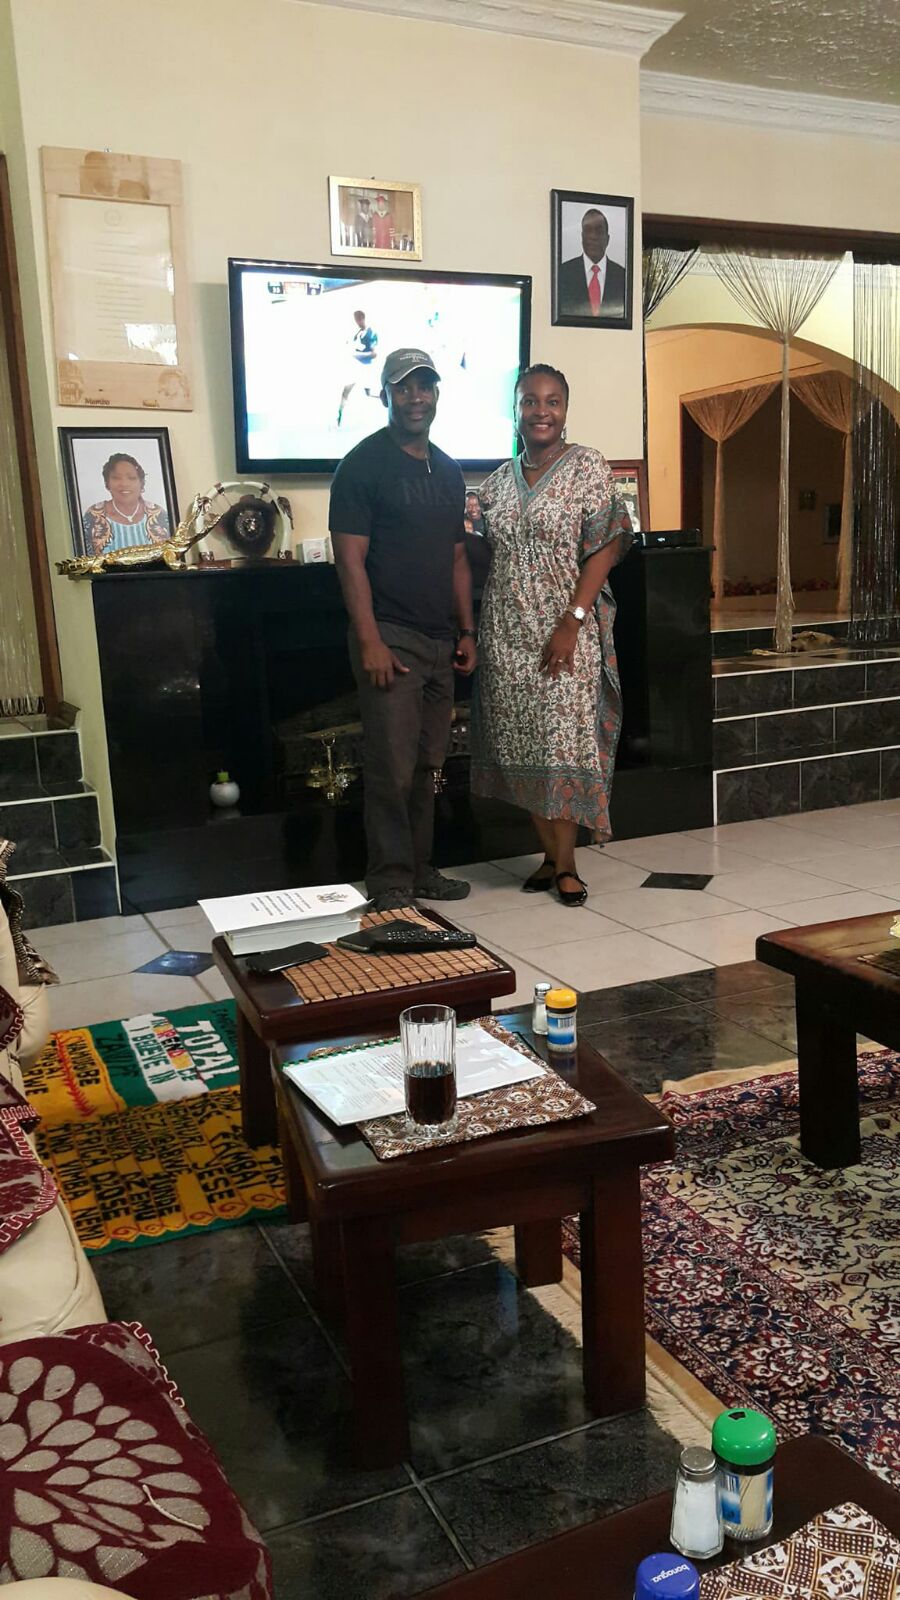
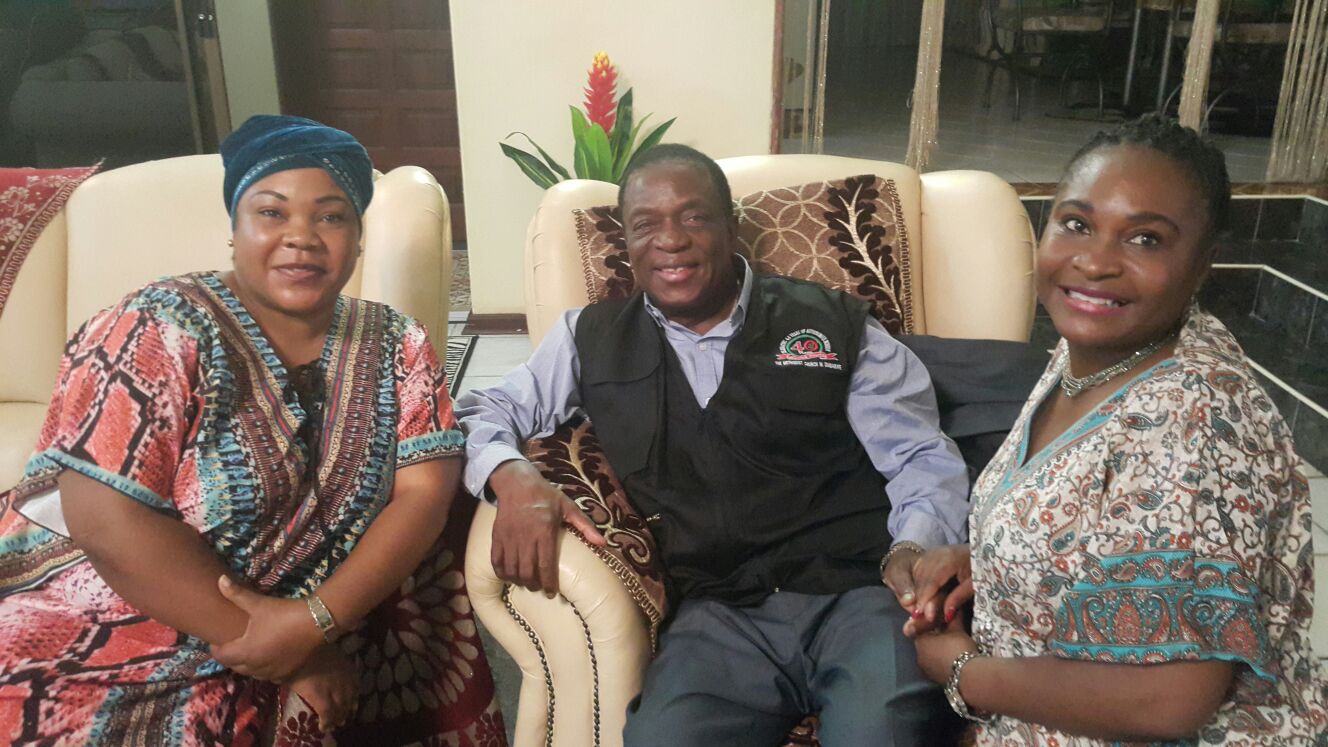
Norton MP Temba Mliswa who claims to be an Independent Member Of Parliament May be lying to Zimbabweans all along. Waltermagaya journalists have found out that Temba Mliswa and his sisters frequent Emmerson Mnangagwas house. 

Two of Temba Mliswa”s sister are both Zanu PF members. With ranking positions and making money using their positions.Mary Mliswa is a Zanu PF MP for Hurungwe and rumors are that Temba Mliswa actually runs Hurungwe and his sister is just a figure head. 

Temba Mliswa pretends to be a strong critic of Emmerson Mnangagwa but the truth is that Temba has been advising the president on a number of issues. Temba has secretly become President Emmerson Mnangagwas whisperer. 

Most critics of the president don’t wine and dine at his house with his sisters. 

Temba Mliswa over the years has become an untouchable and has been accused of corruption and taking over farms by force and to everyone’s surprise he is never arrested or investigated.

Temba Mliswa was In charge of the corruption inquiry which investigated Sir Wicknell Chivayo and the $5 Million Zesa solar energy tender. Why would Temba Mliswa someone with multiple accusations of corruption be the chairman of such an investigation. 

Temba Mliswa has a long Record of criminal activity but has become so powerful in Zimbabwean politics. With the images posted its no surprise why Temba and his sisters have become wealthy  using Zanu PF resources and influence. Temba Mliswa is Zanu PF and has always been a Zanu PF member. He is been fooling everyone by pretending to be an Independent member of Parliament while secretly working with President Emmerson Mnangagwa.

  • Share:

Info News

Cloud Backup for Small Business: Ransomware Protection Guide

Small businesses depend on data to operate. Customer records, invoices, payroll files, email, accounting systems, photos, contracts, point-of-sale data, and shared documents can be just as important as physical inventory. When data disappears because of ransomware, hardware failure, theft, fire, accidental deletion, or a cloud account mistake, business can stop immediately. Cloud backup helps reduce that risk.

Cloud backup is a process that copies data from computers, servers, applications, or cloud platforms to secure off-site storage. The goal is simple: if the original data is lost or damaged, the business can restore a clean copy. Good backup planning is not just about storage; it is about recovery.

Ransomware is one of the biggest reasons small businesses review backup strategy. Criminals may encrypt files and demand payment for a decryption key. If backups are connected to the same network and can be deleted or encrypted, they may not help. Strong backup systems use separation, access controls, retention, versioning, and sometimes immutable storage to prevent attackers from destroying recovery points.

Hardware failure is another common risk. A server drive can fail, a laptop can be dropped, a desktop can crash, or a storage device can stop working. If files are only stored on one machine, one failure can become a crisis. Cloud backup creates an off-site copy that is not dependent on the same hardware.

Accidental deletion may be the most ordinary but frequent problem. Employees may overwrite spreadsheets, delete folders, remove email, or sync bad changes across devices. Version history and point-in-time restore can help recover earlier copies.

A strong backup plan starts with identifying critical data. List servers, desktops, laptops, accounting systems, email, cloud drives, databases, websites, and line-of-business applications. Then decide how often each system must be backed up. A business that enters orders all day may need frequent backups. A file archive may only need daily backup.

Two recovery metrics matter: recovery point objective and recovery time objective. Recovery point objective asks how much data the business can afford to lose. Recovery time objective asks how fast systems need to be restored. These numbers guide the backup frequency, storage type, and service level.

Small businesses should also test restores. A backup that has never been tested is only a hope. Schedule periodic restore tests for files, folders, email, and critical applications. Document the steps and who is responsible. Testing can reveal missing data, slow recovery, password issues, or misunderstood vendor processes.

Security is essential. Backup accounts should use multifactor authentication, role-based access, strong passwords, and limited administrator rights. Backup logs should be reviewed. Alerts should notify the business if backups fail. Encryption should protect data in transit and at rest.

Cloud backup is different from file sync. Services that sync files across devices are convenient, but they may also sync deletions, corruption, or ransomware-encrypted files. Sync can be part of productivity, but it should not be the only backup strategy.

When comparing providers, ask these questions: What platforms are supported? How often are backups taken? How long are versions retained? Is storage immutable? How fast can data be restored? Are full system images supported? Are cloud applications like Microsoft 365 or Google Workspace backed up? Is support available during an emergency? Are restore tests included?

Costs vary based on data volume, number of devices, retention period, support level, and disaster recovery features. The cheapest plan may only back up files, while a more advanced plan may include server imaging, virtualization, and rapid recovery.

Cloud backup protects more than files. It protects revenue, reputation, customer trust, and business continuity. The best time to build a backup plan is before an outage. Once data is encrypted or deleted, options become limited. A tested backup system can turn a disaster into a manageable recovery.

Best Debt Consolidation Loans for Bad Credit in 2026

Trying to manage multiple debts at the same time can feel exhausting. One payment is due Monday. Another hits Friday. Interest keeps growing while your credit score drops lower every month.

That’s why so many people are searching for the best debt consolidation loans for bad credit in 2026. The right loan can simplify payments, reduce stress, and sometimes lower your overall interest rate.

But here’s the truth. Some lenders help people recover financially. Others trap borrowers in even deeper debt.

You need to know the difference.

What Is a Debt Consolidation Loan?

A debt consolidation loan combines multiple debts into one single loan.

Instead of juggling:

  • Credit card balances
  • Medical bills
  • Personal loans
  • Payday loans
  • Collection accounts

You make one monthly payment.

For many borrowers, that structure feels far easier to manage.

Can You Get Approved With Bad Credit?

Yes, but approval depends on several factors.

Lenders usually review:

  • Credit score
  • Monthly income
  • Debt-to-income ratio
  • Employment history
  • Existing loan balances

Some lenders specialize in helping borrowers with lower credit scores.

Others focus only on prime borrowers.

That’s why comparing offers matters.

Best Features to Look for in Debt Consolidation Loans

Not all debt consolidation loans are worth taking.

Some create more financial damage long term.

Here’s what experienced borrowers watch closely.

Fixed Interest Rates

Variable rates can become dangerous.

Your monthly payment may increase unexpectedly.

A fixed-rate debt consolidation loan gives predictable payments, which helps with budgeting.

No Prepayment Penalties

Some lenders charge fees if you pay the loan off early.

That’s a major red flag.

The best debt consolidation loans for bad credit usually allow extra payments without penalties.

Fast Funding

If collection accounts are growing or credit cards are maxed out, speed matters.

Some online lenders fund loans within 24 to 48 hours.

That can help stop financial pressure quickly.

Warning Signs to Avoid

Bad-credit borrowers are often targeted by predatory lenders.

You need to stay alert.

Extremely High Interest Rates

Some lenders advertise “easy approval” while charging massive rates.

That can trap borrowers in long-term debt cycles.

Always compare APRs carefully.

Upfront Fees

Be careful with companies demanding large fees before approval.

Legitimate lenders usually disclose fees clearly within loan terms.

Guaranteed Approval Claims

No real lender guarantees approval without reviewing financial information.

That’s often a sign of a scam.

How Debt Consolidation Can Affect Your Credit Score

This depends on how the loan is managed.

Debt consolidation may help your score if:

  • You make on-time payments
  • Credit card utilization drops
  • Old balances get paid off
  • Collections stop growing

But missed payments can still damage your credit.

The loan itself is not magic. Financial discipline still matters.

Secured vs Unsecured Debt Consolidation Loans

There’s a major difference between these loan types.

Secured Loans

Secured loans require collateral.

This may include:

  • A vehicle
  • Home equity
  • Savings accounts

Rates are often lower, but the risk is higher.

If you default, you could lose the asset.

Unsecured Loans

These loans do not require collateral.

Approval is usually harder for borrowers with poor credit, but they reduce the risk of losing personal property.

Alternatives to Debt Consolidation Loans

Sometimes consolidation is not the best solution.

Other options may include:

  • Credit counseling
  • Debt settlement
  • Balance transfer cards
  • Negotiating directly with creditors
  • Bankruptcy consultation

Each option has pros and cons.

The right choice depends on your financial situation.

How to Improve Approval Chances

Want better loan offers?

Here are practical steps that can help.

  • Pay down small balances first
  • Avoid opening new credit accounts
  • Increase monthly income if possible
  • Check your credit report for errors
  • Reduce unnecessary spending

Even small improvements may lead to better rates.

Why Debt Consolidation Keywords Have High CPC

Financial services companies compete aggressively for qualified borrowers.

Lenders know customers searching for debt consolidation loans often convert into long-term clients.

That’s why these keywords attract heavy advertising competition and strong CPC values.

Final Takeaway

The best debt consolidation loans for bad credit in 2026 can help simplify your finances, reduce stress, and create a path toward recovery.

But not every lender has your best interests in mind.

Take time to compare loan terms carefully, avoid predatory offers, and focus on long-term financial stability instead of quick fixes.

A smart decision today can prevent years of financial pressure later.

FAQ

What credit score is needed for a debt consolidation loan?

Some lenders approve borrowers with scores below 600, though rates may be higher.

Will debt consolidation hurt my credit score?

It may temporarily lower your score slightly, but responsible repayment can improve credit over time.

Are online debt consolidation lenders safe?

Many are legitimate, but borrowers should research reviews and verify lender credentials carefully.

Can debt consolidation stop collection calls?

Paying off accounts through consolidation may reduce collection activity.

Is debt consolidation better than bankruptcy?

It depends on the amount of debt, income level, and long-term financial goals.